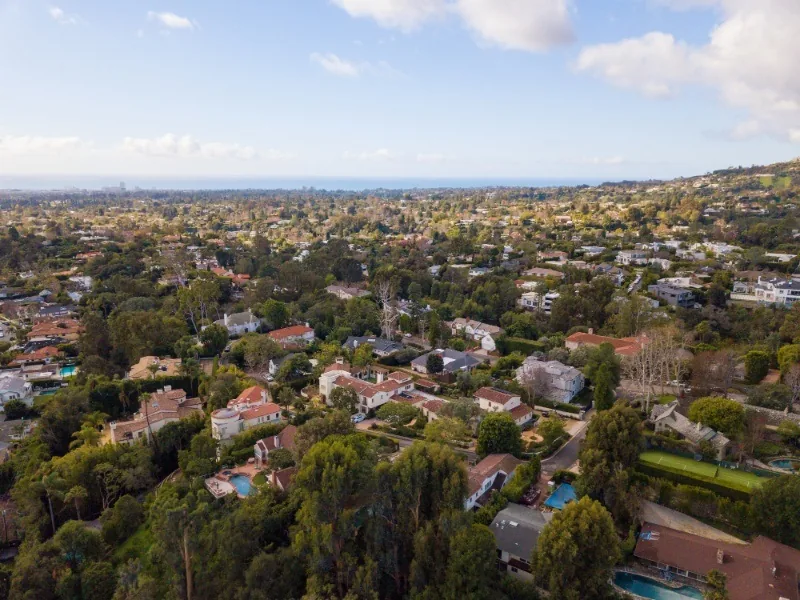
A condo or townhome purchase in Brentwood or Venice turns on documents a house purchase never involves. You are buying into a corporation as well as a property, and the association's finances, its rules and its insurance can matter more to your costs and your plans than anything inside the unit. The two neighborhoods also behave differently: Brentwood's inventory skews to larger, lower-density buildings on the Wilshire corridor and in the flats, Venice's to small conversions, walk-street buildings and newer infill near Abbot Kinney. My family has been on the Westside for five generations and I have sold across this coastline for 18 years. Here is what I check before a client commits.
What actually changes when you buy a condo instead of a house?
You acquire two things rather than one: your unit, and an undivided interest in everything outside it, governed by an association you automatically join.
That association sets a monthly assessment, holds the insurance on the building's structure, controls what you may change, and can levy a special assessment against you for work the reserves do not cover. None of that appears in the listing price. A unit that looks well priced against a comparable house can carry obligations that change the arithmetic entirely, and a unit that looks expensive can be the better buy if the association is well run.
In California the seller must deliver a defined set of association documents once you are in contract. That delivery is the single most useful thing in the transaction and it is where I spend most of my attention.
Which documents decide whether it is a good buy?
Five, and they are not equally weighted.
| Document | What it tells you | What a problem looks like |
|---|---|---|
| Reserve study | Whether the association has saved for the roof, plumbing, elevators and deck work it knows are coming | A low percent funded figure alongside major components near end of life |
| Board minutes | What the building is actually arguing about, months before it reaches a disclosure | Repeated discussion of leaks, litigation, or a deferred capital project |
| CC&Rs and rules | What you may renovate, lease, park and keep | Leasing caps or minimum lease terms that conflict with your plans |
| Master insurance policy | What the association covers and where your own policy must start | A high master deductible the association can pass through to owners |
| Budget and assessment history | Whether dues are keeping pace with costs | Dues held flat for years while insurance and labour rose |
Dues held artificially low are not a bargain. They are a special assessment arriving later, and the owner holding title when the board votes is the one who pays it.
How is buying in Venice different from buying in Brentwood?
The building stock is the main difference, and it drives almost everything else.
Venice has a large share of older, smaller buildings, including conversions and walk-street properties. Older construction in the City of Los Angeles raises questions a newer building does not: whether the building fell under the city's soft-story retrofit requirements and whether that work was completed and signed off, what the plumbing and electrical have had done, and whether any part of the property sits in a coastal zone where alterations need an additional layer of approval. Several Venice buildings also sit close enough to the beach that the association's insurance history is worth reading closely.
Brentwood's condo inventory is weighted toward larger buildings, a good number of them on or near the Wilshire corridor, with full-time staff and more conventional association structures. The questions there tend to be about reserve adequacy in buildings with expensive shared systems, elevators, subterranean parking and common HVAC, rather than about retrofit status.
One rule that applies in both: if you intend to lease the unit at any point, check the association's leasing provisions and the city's rental regulations before you are in contract, not after. Older buildings in the City of Los Angeles can fall under rent stabilization depending on the building's age and configuration, and that materially affects what you can do with the property. Verify the specific unit rather than relying on a general assumption about the neighborhood.
What should you expect to pay beyond the purchase price?
Monthly assessments, your own interior insurance policy, and the possibility of a special assessment.
Your own policy is the part buyers most often underestimate. The association's master policy typically covers the building's structure to a defined point, and your policy picks up from there, covering interior finishes, personal property, loss of use and liability. Where that line falls is set in the CC&Rs and the master policy, and it varies between buildings. Read both and have your insurance broker read them too, before you waive contingencies.
Insurance on the Westside has become materially harder since the January 2025 fires, which affects associations as well as individual owners. An association facing a sharp renewal increase has to fund it from somewhere, and that usually means dues or an assessment. I have written separately about how insurance on the Westside works now, and the same market pressures reach condo associations.
On a sale above the City of Los Angeles transfer tax thresholds, that tax applies to condos exactly as it does to houses. It is calculated on the gross price, not on your equity, which surprises sellers more often than buyers.
How do you judge an association you cannot see inside?
Read the minutes first, then the reserve study, then everything else.
Minutes are the honest document. A disclosure packet tells you what the association is obliged to tell you; the minutes tell you what the owners have actually been arguing about for the last two years. Leaks, parking disputes, a contractor who did not finish, a board that cannot reach quorum, early discussion of a project nobody has priced yet. Those appear in minutes long before they appear anywhere else.
Then test the reserve study against them. If the minutes discuss a roof and the reserve study funds a roof, the association is being run properly. If the minutes discuss a roof and the reserve study does not mention one, you have found the thing that will cost you money.
Ask how many units are owner occupied, how many are leased, and whether any are owned by the same party. Ask whether the association is in litigation, and if so, with whom and about what. Ask when dues last rose and by how much. A board that answers those quickly is usually a board worth buying into.
Is a townhome a better option than a condo?
Sometimes, and the distinction is about what you own rather than how it looks.
Townhomes in this market are frequently still condominiums in legal structure, with an association and shared components, even where each unit has its own entrance and no shared walls above and below. Others are structured so that the owner holds the land beneath the unit. Those are different purchases with different obligations, and the listing language will not reliably tell you which one you are looking at.
Check the legal description and the CC&Rs rather than the marketing. If you want the autonomy of a house, that is achievable in this market, but you have to buy the right structure rather than the right floor plan.
Where to take this next
If you are weighing a specific building, the fastest way through is to get the association documents early and read them properly, rather than at the end of a contingency period when there is no time to react.
I can usually tell within an hour of reading minutes and a reserve study whether a building is well run. If you are comparing two units in different buildings, that reading is often the whole decision. For how these neighborhoods compare more broadly, I have written about Santa Monica and Venice and about Brentwood against the other Westside communities.
Frequently Asked Questions
Are there luxury condos and townhomes in Brentwood and Venice?
Yes, and the two markets differ in character. Brentwood's inventory leans toward larger buildings with shared staff and systems, a good number near the Wilshire corridor. Venice has more small buildings, conversions and newer infill, including walk-street locations close to the beach.
What documents should I read before buying a condo in Los Angeles?
The reserve study, the board minutes, the CC&Rs and rules, the association's master insurance policy, and the budget with its assessment history. In California the seller is required to deliver a defined set of these once you are in contract.
What is a special assessment and how likely is one?
A special assessment is a one-off charge levied on owners for work the reserves do not cover. Likelihood is best judged from the reserve study's funding level alongside the age of major components, and from whether the minutes discuss projects that have not yet been funded.
Does the association's insurance cover my unit?
Usually only to a defined point. The master policy typically covers the building structure, and your own policy covers interior finishes, personal property, loss of use and liability. Where the line falls is set in the CC&Rs and the master policy and differs between buildings, so both should be read before contingencies are waived.
Can I lease out a Brentwood or Venice condo?
That depends on the association's leasing provisions and on the city's rental regulations for that specific building. Some associations cap the number of leased units or set minimum lease terms. Older buildings in the City of Los Angeles may fall under rent stabilization depending on age and configuration. Verify the specific unit before you are in contract.
Is a townhome legally different from a condo?
Often not. Many townhomes in this market are condominiums in legal structure, with an association and shared components, even where the unit has its own entrance. Others are structured so the owner holds the land beneath. Check the legal description and CC&Rs rather than the marketing description.
Does the city transfer tax apply to condo sales?
Yes. Where a sale exceeds the City of Los Angeles transfer tax thresholds, the tax applies to condominiums on the same basis as houses, calculated on the gross sale price rather than on the seller's equity.
Let's look at the building you are considering
Most condo decisions in these two neighborhoods come down to how a specific association is run, and that is knowable before you commit. If you send me the address, I will tell you what I know about the building and what I would want to read first.
Call me at 310-595-5181 or reach out through the site.
Monica Antola, Broker Associate, Compass. DRE# 01826288.